Smart Tax Planning Strategies for Santa Monica Business Owners
By Gill
20 Views
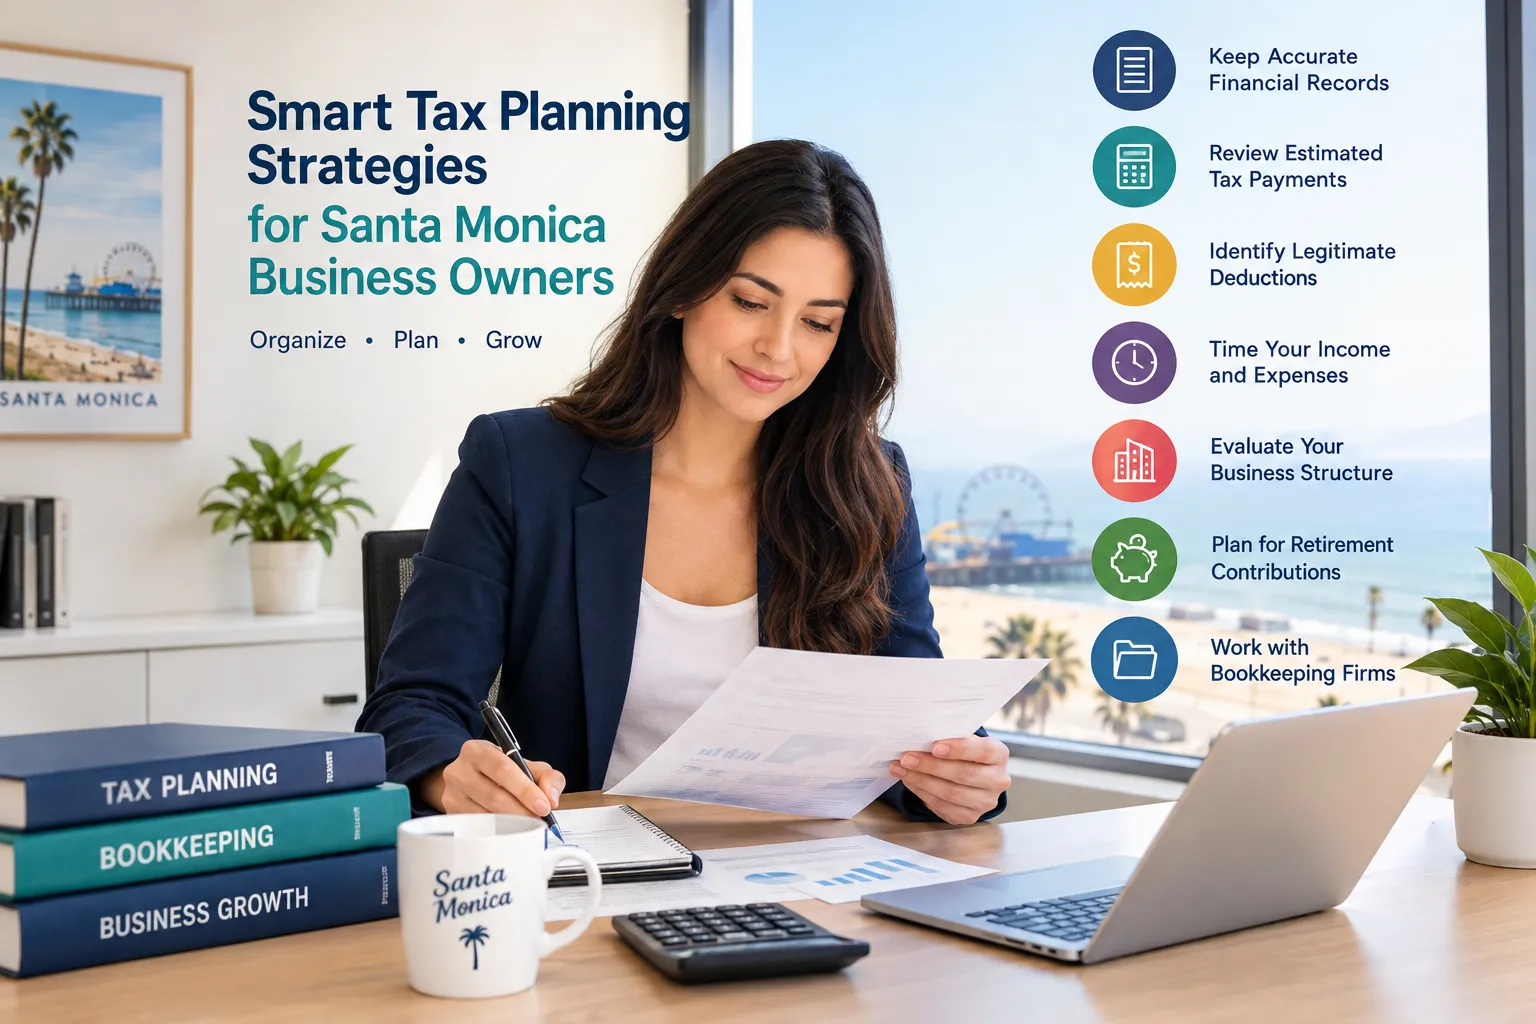
Tax planning is easier when it starts before tax season. For business owners in Santa Monica, a good plan can help organize finances, anticipate tax obligations, identify legitimate deductions, and reduce the risk of last-minute surprises. The goal isn't simply to prepare a return after the year ends. It is to make informed financial decisions throughout the year.
Effective tax planning strategies Santa Monica businesses use should consider income, expenses, business structure, payroll, estimated payments, retirement contributions, and recordkeeping. Local obligations can also make accurate financial records especially important.
Start With Accurate Financial Records
One of the simplest ways to improve tax planning is to keep business records current. If income and expenses aren't categorized correctly, it becomes difficult to estimate taxable profit or determine whether potential deductions have been properly documented.
Your records should generally separate business and personal transactions. Bank accounts, credit cards, invoices, receipts, payroll records, and loan documents should be organized so financial information can be reviewed throughout the year.
Monthly reconciliation is particularly useful. It can uncover duplicate transactions, missing expenses, incorrect income classifications, and other bookkeeping issues before they become bigger problems.
For businesses that don't have the time or internal staff to maintain these records, working with bookkeeping firms can provide ongoing financial organization and reporting support.
Review Estimated Tax Payments Regularly
Business income can change significantly during the year. A company may experience a strong quarter followed by a slower period, or an owner may receive additional income from another source.
Instead of relying entirely on an estimate made months earlier, review projected income and tax obligations periodically. Changes in revenue, deductible expenses, payroll, or business structure can affect the amount that should be set aside.
A mid-year tax review can be especially useful because it gives business owners time to make appropriate adjustments before the end of the year.
Identify Legitimate Business Deductions
Deductions can reduce taxable business income when expenses qualify under applicable tax rules. The important point is that deductions should be based on actual, properly documented business expenses rather than simply trying to increase the number of write-offs.
Depending on the business, potentially relevant expenses may include:
- Professional services
- Business insurance
- Advertising and marketing
- Office supplies
- Software subscriptions
- Certain travel expenses
- Payroll and employee-related costs
- Business equipment
- Professional education
- Qualified home-office expenses
The rules can vary based on the type of expense and how the business operates. Good documentation should show what was purchased, when it was purchased, how much it cost, and why it was related to the business.
Consider the Timing of Income and Expenses
The timing of revenue and expenses can sometimes affect the tax picture for a business. Depending on the accounting method and applicable tax rules, owners may need to consider when income is recognized and when certain expenses are incurred.
This doesn't mean delaying or accelerating transactions simply to create a tax benefit. Instead, it means understanding how planned financial activity could affect taxable income.
For example, a business expecting unusually high income may benefit from reviewing planned equipment purchases, employee bonuses, retirement contributions, or other legitimate year-end expenses with a qualified tax professional before taking action.
Review Your Business Structure
Business structure can have important tax consequences. Sole proprietorships, partnerships, LLCs, S corporations, and C corporations can have different reporting requirements and tax considerations.
As a business grows, the structure that worked during its early stages may no longer fit its financial situation. Revenue, payroll, ownership, administrative requirements, and long-term goals can all be relevant when reviewing the structure.
A business owner should not change entity structure solely because someone promises a certain tax savings amount. The decision should consider the complete financial and administrative impact.
Plan for Retirement Contributions
Retirement planning can be another component of a broader tax strategy. Depending on eligibility and the retirement plan selected, business owners may have opportunities to contribute to accounts such as a SEP IRA, Solo 401(k), or other qualified retirement arrangement.
These decisions can involve contribution limits, deadlines, employee considerations, and other rules. Planning earlier in the year gives owners more time to understand their options rather than making rushed decisions near year-end.
Retirement contributions can also connect business tax planning with long-term personal financial goals, making them worth discussing as part of an overall financial plan.
Keep Santa Monica Business Obligations in View
Local business requirements should not be overlooked when planning business finances. Santa Monica businesses may have city-specific licensing and tax obligations in addition to federal and California requirements.
Current local guidance indicates that Santa Monica's business license tax is based in part on gross receipts and business classification, with reporting and renewal requirements that differ from ordinary federal income tax deadlines. Keeping revenue records clean throughout the year can make these obligations easier to manage.
Sales tax and payroll responsibilities may also involve separate reporting systems and agencies. For that reason, business owners should avoid treating all taxes as one single obligation.
Use Bookkeeping to Support Better Tax Decisions
Tax planning depends heavily on the quality of the financial information behind it. A profit and loss statement that contains incorrect categories or unreconciled accounts can lead to poor decisions.
A consistent bookkeeping process can provide useful information such as:
- Monthly revenue
- Operating expenses
- Accounts receivable
- Accounts payable
- Payroll costs
- Estimated profit
- Cash flow trends
- Outstanding liabilities
This information allows business owners and their tax professionals to identify potential issues earlier.
Professional bookkeeping support may also be helpful for businesses dealing with multiple revenue streams, employees, inventory, sales tax, or more complicated financial transactions. The right bookkeeping firms can help maintain organized records, but business owners should still understand their financial reports and tax responsibilities.
Build a Year-Round Tax Planning Calendar
Waiting until tax filing season often creates unnecessary pressure. A simple annual calendar can make the process more manageable.
Consider scheduling regular reviews for:
- Monthly bookkeeping reconciliation
- Quarterly income and expense reviews
- Estimated tax payment planning
- Payroll and tax liability checks
- Retirement contribution planning
- Mid-year tax projections
- Year-end deduction and expense review
- Preparation of tax documents before filing deadlines
This approach turns tax planning into an ongoing financial process instead of a once-a-year activity.
Avoid Last-Minute Tax Decisions
One of the biggest problems with reactive tax planning is limited time. When the year is nearly over, there may be fewer opportunities to evaluate options carefully.
For example, an owner might discover that estimated payments were too low, financial records are incomplete, or an important retirement contribution requires advance planning. These issues are easier to address when they're identified months earlier.
Proactive planning also gives business owners an opportunity to ask questions and understand the potential tax consequences before making significant financial decisions.
Final Thoughts
Good tax planning isn't about finding a single trick that works for every business. It is about understanding your numbers, maintaining reliable records, monitoring income and expenses, and making financial decisions with tax consequences in mind.
For Santa Monica business owners, the process should also account for applicable federal, California, and local requirements. Regular bookkeeping, timely financial reviews, and professional tax guidance can make the process more organized and easier to manage.
The most useful tax planning strategies Santa Monica business owners can adopt are usually the ones that become part of their normal financial routine. When accurate records and forward-looking planning work together, tax decisions become less reactive and more informed.
Related Reading
Top 10 Hidden Secrets About Business & Finance You Need to Know
Welcome to our in-depth exploration of Business & Finance. In an era defined...
Why Business & Finance is Transforming the Global Industry Landscape
Welcome to our in-depth exploration of Business & Finance. In an era defined...